Rates & Refinancing

Rate-and-Term or Cash-Out? Follow the Money

Both replace your first mortgage. The difference is whether you are changing the loan terms or also borrowing against your equity.

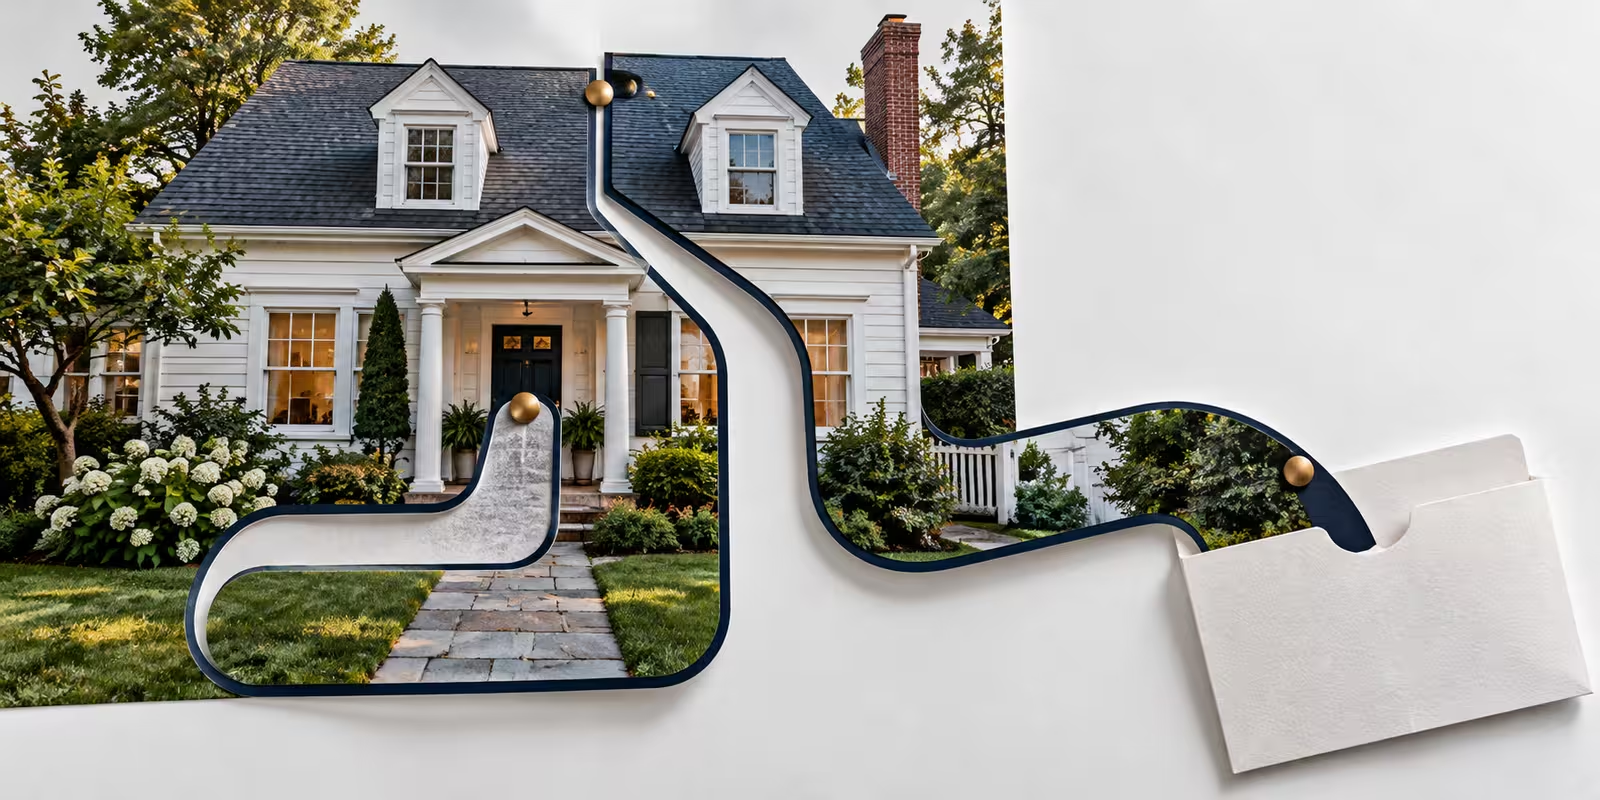
A photo of a white house split into two navy-edged paper paths: one loops back into the house, one opens into an empty paper pocket

Quick Facts: Two Refinance Purposes

  • Change terms

    Rate, term or structure.

  • Borrow cash

    Cash-out adds a new obligation.

  • Retained equity

    Value minus secured debt.

  • Whole-loan view

    Compare total balances and costs.

Two purposes, two obligations

Start with the purpose. Do you want to change how the loan is repaid, or borrow additional money? Neither route automatically gives you a lower payment or better rate.
Rate-and-term

Rate-and-term

Generally changes rate, term or structure without substantial cash out. Permitted costs may be financed; limited cash back and classification follow program rules.
Cash-out

Cash-out

A new mortgage repays the existing one and releases eligible equity as borrowed cash. It creates a new balance and repayment obligation.

Follow every dollar through closing

Simplified cash-out illustration

  • $370,000 New loan
  • $300,000 Existing payoff
  • $8,000 Costs paid from proceeds
  • $62,000 Illustrative net cash

Not an offer or lending limit. Actual proceeds depend on the payoff statement, liens, costs, escrows and program rules.

Where the assumed property value goes

$500,000 assumed value · $370,000 new loan

$370,000 New mortgage · 74%

$130,000 Retained equity · 26%

Estimated equity from the assumed value, not cash available in a bank account. This is not an eligibility or maximum-LTV rule.
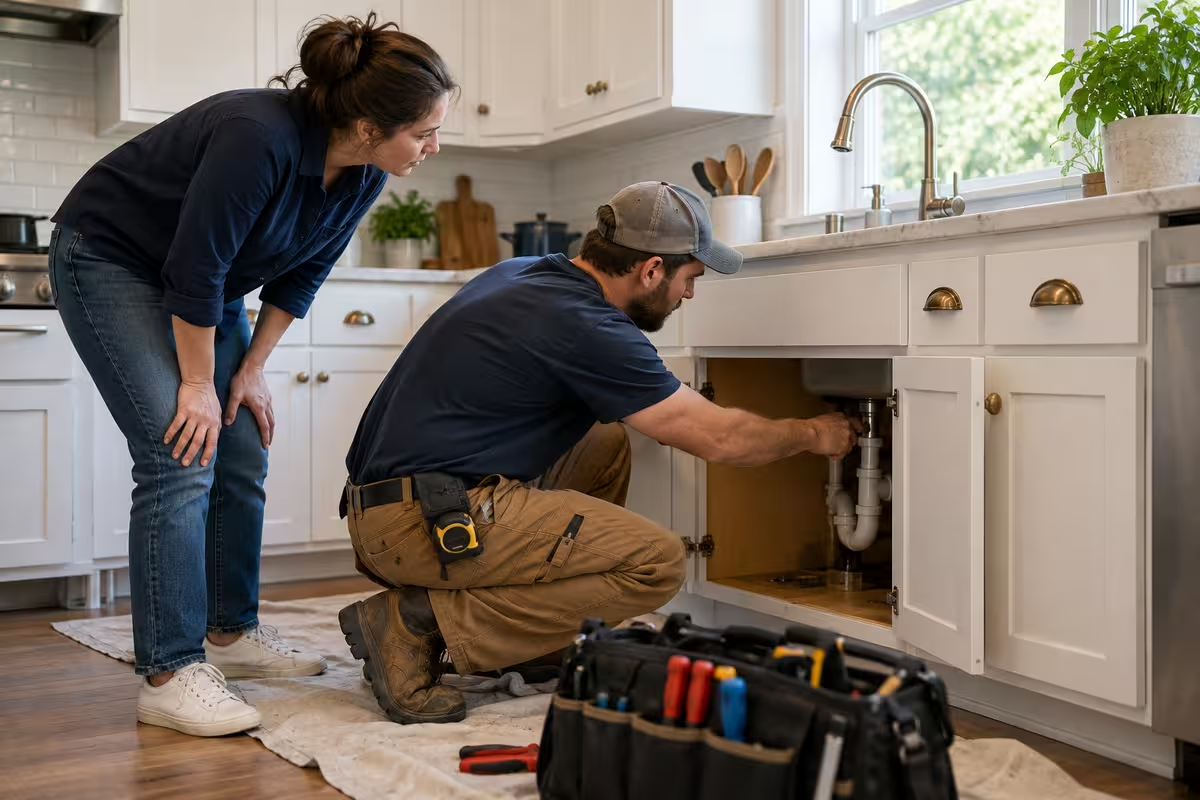
Give the cash a specific job

A homeowner reviews a practical renovation with a tradesperson.

For a renovation, set a realistic budget and contingency. Improvements do not guarantee an equal increase in the home’s value.

For consolidation, compare fees, total interest and time to repay. Turning unsecured debt into debt secured by your home changes the consequences of missed payments.

Compare the whole loan, not only the new cash

Separate paper paths represent different financing structures.

Cash-out replaces the first mortgage. If the new rate is higher, repricing applies to the refinanced balance as well as the additional borrowing.

A home equity loan or HELOC may leave that first mortgage in place, while adding a payment and lien. A HELOC can have a variable rate and different repayment after the draw period.

How rate-and-term, cash-out and home equity borrowing compare
Structure First mortgage What to compare
Rate-and-term Replaced Fees, new balance, payment and payoff horizon.
Cash-out Replaced Those items plus net cash, equity retained and the rate on the full balance.
Home equity loan / HELOC May stay in place Combined payments, fees, term, rate risk and later repayment changes.

Ask for the complete written breakdown

  • Cash needed and cash received

    What will I actually receive after every payoff and charge?

  • Complete new debt

    Which costs or other obligations are financed?

  • Same comparison horizon

    What are combined payments and total costs over my intended term?

  • Equity and reserves afterward

    What remains in the property, and what cash can I access?

Compare actual offers for the same cash need. Future equity access depends on value, income, credit and available financing. Tax treatment depends on your circumstances and use of funds.

Sources & further reading

  1. CFPB: Should I refinance? (opens in a new tab)
  2. CFPB: Cash-out refinancing and borrower risks (opens in a new tab)
  3. CFPB: Compare Loan Estimates (opens in a new tab)

Was this article helpful?

The Bottom Line

Choose the borrowing structure after defining the goal. Compare the cost of the whole mortgage, the cash you actually receive and the equity and reserves you will retain.

Let’s Connect

Talk with a licensed loan officer.

This article is for general educational purposes only and isn’t a commitment to lend or an offer of credit. Loan programs, rates, fees, and eligibility vary by lender and borrower and may change without notice. Talk with a licensed loan officer about your situation.