Credit & Mortgage Readiness

Credit Score Tune-Up: Start with the Report

Start with accurate reports, on-time payments and manageable balances. A stronger application begins with the basics—not a promised score jump.

A magnifying glass over a ruled report sheet, navy paper bars, a bronze binder clip and a leather wallet

Quick Facts: Credit Preparation

  • Check the records

    Start with accurate information.

  • Pay on time

    Protect a consistent payment history.

  • Manage balances

    No ratio guarantees a score.

  • Plan ahead

    Discuss changes with your lender.

Start with the information behind the number
A borrower reviewing credit records.

Preparing early gives you time to check reports and address errors. Look for accounts that are not yours, incorrect late payments, duplicate debts and balances that do not match your records.

Use the reporting company’s dispute process and keep evidence. Accurate negative information is different from an error. No tactic promises a particular point increase.

What shapes a FICO score?

FICO groups credit information into five broad categories. These percentages describe general importance across the population; their effect varies by person.

FICO® score factors GENERAL IMPORTANCE
  • Payment history Whether accounts have been paid as agreed. 35%
  • Amounts owed Debt information, including revolving utilization. 30%
  • Length of history How long credit accounts have been established. 15%
  • New credit Recent applications and new accounts. 10%
  • Credit mix The types of credit in the file. 10%

Amounts owed is broader than credit-card utilization. Other scoring models can evaluate a file differently. Lenders also review income, debts and the proposed mortgage.
A lower balance is one part of the picture

Utilization compares reported revolving balances with available credit. Overall usage and individual accounts can both matter.

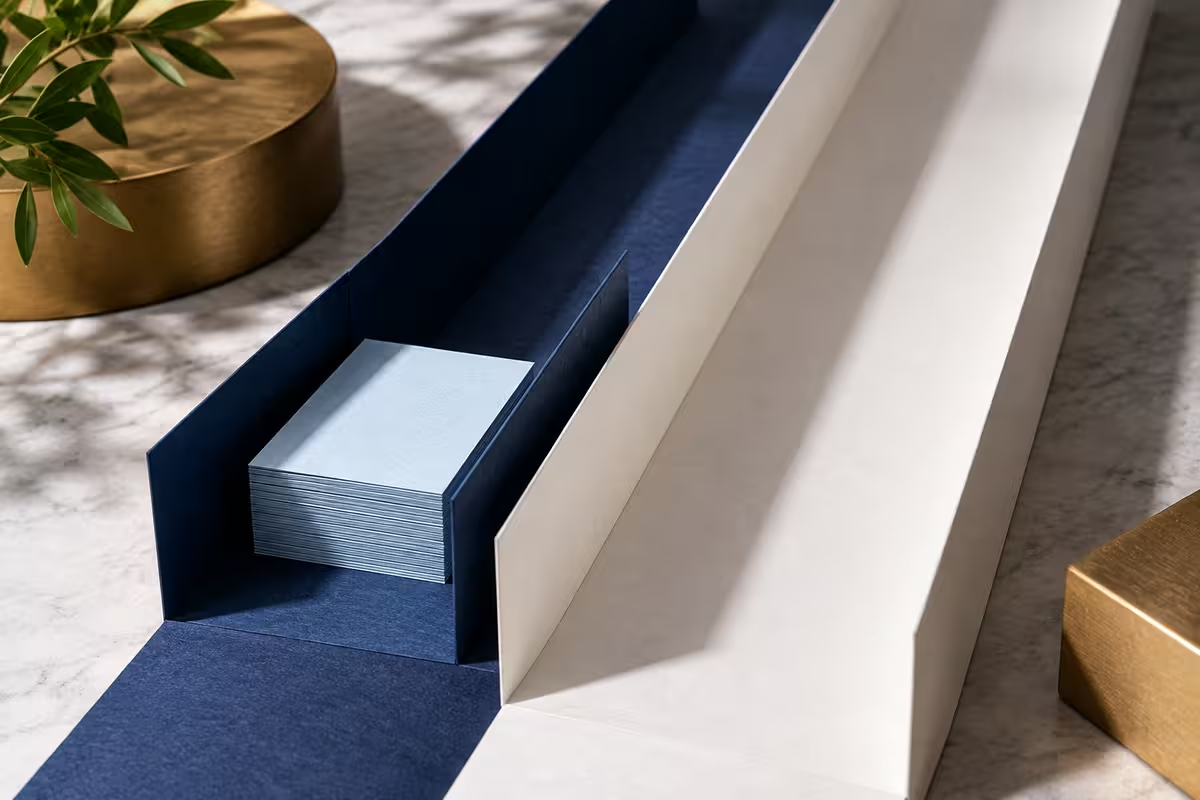
One card · illustrative ratio

Reported balance $500

Available limit $5,000

Utilization 10%

10% used 100% limit

A ratio, not a recommended target or a guaranteed score result.

Paper channels illustrate used credit and available capacity.

Payment due dates and reporting dates are not always the same. Ask the issuer how it reports, and confirm updated information appears.

Keep enough cash for your purchase and reserves while reducing debt. Discuss proposed payoffs with your loan officer.

Build a routine you can sustain

A clock and calendar support an organized payment routine.
  1. Review all three nationwide reports and keep supporting records.
  2. Protect payments with reminders or suitable autopay; monitor the funding account.
  3. Follow up on factual corrections before the lender’s credit review.

This is a planning sequence, not a promised correction or score-improvement timeline.

Review big moves before you make them

A homeowner organizes a credit preparation plan.

A credit move can affect both the score and the wider mortgage application. Keep your lender informed through closing.

Credit moves and what to review before making them
Action What to review
Close an unused card Available credit, utilization, fees and fraud risk.
Open a new account The inquiry, new debt and effect on the mortgage file.
Pay or dispute a collection Accuracy, timing and program requirements; no automatic score increase.
Co-sign or finance a purchase New obligations can affect credit and debt-to-income analysis.

Sources & further reading

  1. FICO: What goes into a credit score (opens in a new tab)
  2. CFPB: Common credit report errors (opens in a new tab)
  3. CFPB: Credit scores and mortgage pricing (opens in a new tab)
  4. AnnualCreditReport.com: Official credit report access (opens in a new tab)

Was this article helpful?

The Bottom Line

Credit preparation is a process: verify the information, make payments on time and manage balances. Keep your loan officer informed and give legitimate corrections time to appear.

Let’s Connect

Talk with a licensed loan officer.

This article is for general educational purposes only and isn’t a commitment to lend or an offer of credit. Loan programs, rates, fees, and eligibility vary by lender and borrower and may change without notice. Talk with a licensed loan officer about your situation.